The China Syndrome
by Satyajit Das
In 1971, Ralph Lapp, a nuclear physicist, used the term "China syndrome" to describe a hypothetical nuclear reactor meltdown where the molten core breaches containment barriers and melts through the crust of the Earth reaching China. The economic equivalent of the China Syndrome describes a process in which China's strong growth, abundant savings and foreign exchange reserves assists a rapid restoration of global growth.
The nuclear metaphor ignores the geographical fact that the opposite side of the globe from the United States is actually the Indian Ocean and that the entire idea is physically impossible. The economic metaphor conveniently discards some significant doubts about the ability of China to act as a catalyst for global recovery.
The Unbalanced Bicycle
China's economic growth model was a contributing factor in the current Global Financial Crisis (GFC).
Under Deng Xiaoping, leader of the Communist Party from 1978, China undertook Gaige Kaifang (Reforms and Openness) – reform of domestic, social, political and economic policy. Economic stagnation and serious social and institutional woes that could be traced to Mao's Cultural Revolution forced the change.
The centerpiece was economic reforms that combined socialism with elements of the market economy. It entailed engagement with the global economy, reversing the traditional policy of economic self-reliance and a lack of interest in trade.
In embracing markets, Deng famously observed that: "It doesn't matter if a cat is black or white, so long as it catches mice." Deng also embraced a change in philosophy: "Poverty is not socialism. To be rich is glorious."
China's economic reforms coincided with the "Great Moderation" – a period of strong growth in the global economy based on low interest rates, low oil prices and deregulation of key industries such as banking and deregulation. The boom was also based on increases in global trade and investment driven, in part, by the fall of the Berlin Wall, the collapse of the Soviet Union and integration of socialist economies into the world economy.
China's growth model, inspired by the post-war recovery of Japan, used trade to accelerate the growth and modernization of its economy. The economic engine was export driven growth.
The model took advantage of China's large, cheap labor force, and the strategy benefited from rising costs in neighboring Asian countries such as Japan, South Korea, Taiwan, Hong Kong and Singapore. China was able to attract significant foreign investment, technology and management and trading skills from countries keen to outsource manufacturing to lower-cost locations to improve declining competitiveness.
China converted itself, at least parts of the country, into the world's factory of choice. It imported resources and parts that were then assembled or processed and then shipped out again. The Great Moderation ensured a growing market for exports.
Innate conservatism, the desire to maintain Communist Party control of the domestic economy and avoid social disruption favored partial market liberalization. China's need to provide employment for its underemployed population and improve its technology also favored this strategy. China's economy needs to grow 7% to 8% annually to absorb workers entering the formal workforce each year.
The strategy was decidedly "trickle down economics" as Deng himself acknowledged: "Let some people get rich first."
As economic momentum increased, foreign businesses invested in China to take advantage of the growth and rising living standards. Opportunities encouraged Chinese nationals living, studying and working overseas to return.
Over time, a novel liquidity system also accelerated growth to staggering levels.
Liquidity Vortex
Export success created large foreign reserves that now total more than $2 trillion. These reserves became the centre of a gigantic lending scheme in which China would finance and thereby boost global trade flows.
Dollars received from exports and foreign investment have to be exchanged into Renminbi. In order to maintain the competitiveness of its exporters, China invests the foreign currency overseas to mitigate upward pressure on the Renmimbi.
As reserve growth paralleled its growing trade surplus, China invested heavily in dollars, helping to finance America's large trade and budget deficits. It is estimated that China has invested 60% to 70% of its $2 trillion reserves in dollar-denominated investments, primarily U.S. Treasury bonds and other high quality securities.
Chinese funds helped keep American interest rates low, encouraging increasing levels of borrowing, especially among consumers. The increased debt fueled further consumption and housing and stock market bubbles that enabled consumers to decrease savings as the ‘paper' value of investments rose sharply. This consumption, in turn, fed increased imports from China, creating further outflows of dollars via the growing trade deficit. The overvalued dollar and an undervalued Renminbi exacerbated excess U.S. demand for imported goods.
In effect, China was lending the funds used to purchase its goods. China never got paid, at least until the loan to America was paid off.
The Asian crisis of 1997-98 encouraged China to build even larger surpluses. Reserves were seen as protection against the destabilizing volatility of short-term foreign capital flows that had almost destroyed many Asian countries during the crisis.
The substantial build-up of foreign reserves in China and the central banks of other emerging countries was a liquidity-creation scheme. The arrangements boosted growth and prosperity in China, other emerging markets and the developed world. Commodity exporters, such as Australia, benefited significantly from the increased demand for commodity and the higher prices for resources.
Fall & Rise
In 2007, unsustainable levels of debt in many economies triggered a near collapse of the global banking system that, in turn, triggered a major slowdown in growth.
The unprecedented external demand shock, with sharp decreases in consumption and investment from synchronous deep recessions in the developed world, affected the Chinese economy. The sudden and precipitous fall in exports led to a significant slowdown in China's stellar growth rates in 2008, triggering sharp declines in stock and property markets.
Job losses in export-intensive Guangdong province were in excess of 20 million migrant workers. Workers and students entering the workforce were unable to find work. Fearful of social instability, the Beijing government moved quickly to restore rapid growth.
Panicked government spending and loose monetary policies increasing available credit are currently driving China's recovery, contributing around 75% of China's growth of 8% to9% in 2009. In the June quarter, Chinese exports (35% to 40% of the economy) decreased by about 20%, implying that the non-export part of the economy grew strongly.
In the first half of 2009, new loans totalled more than $1 trillion. This compares with total loans for all of 2008 year of about $600 billion. Current lending is running at around three times 2008 levels and at a staggering 25% of China's GDP.
The availability of credit is fuelling rampant speculation in stocks, property and commodities. Estimates suggest that 20% to 30% of new bank lending is finding it way into the stock market, driving up values. Record numbers of new trading accounts have been opened, including over 500,000 accounts in one week in July alone, the highest since January 2008.
The market for initial public offerings for new companies has recommenced after being closed for six months. Recent issues have been massively oversubscribed and risen sharply on listing. In July 2009, on the first day of trading, shares in China State Construction Engineering, the country's largest homebuilder, rose by as much as 90%, closing up 56% and reviving memories of the heady days of the previous boom. The shares in Sichuan Expressway tripled on debut before closing up over 200% %. The frenzy has also affected Hong Kong, where China related stocks have risen strongly.
China's recovery, in turn, underpinned the recovery in commodity prices and economies dependent on natural resources. In recent parliamentary testimony, Reserve Bank of Australia Assistant Governor Philip Lowe highlighted the extent to which Australia, a major trading partner of China, was reliant on Chinese demand. Lowe noted that 23% of Australia's total exports went to China in the most recent quarter, up from 4% 10 years ago. China now also takes 80% of Australia's iron ore exports and 20% of coal exports.
While a significant part of the importation of commodities is restocking depleted inventory, abundant and low cost bank finance combined with a deep seated fear of the long-term prospects of U.S. Treasury bonds and the dollar has encouraged speculative stockpiling artificially boosting demand.
Lock & Load
Government spending and bank loans have resulted in sharp increases in fixed asset investments (up more than 30% from 2008). A major component is infrastructure spending, which accounts for more than 70% of the Chinese government's stimulus package. In the first half of 2009, investment accounted for more than 80% of growth, approximately double the 43% average contribution over the last 10 years.
Infrastructure investment is adding to production capacity in a world with sluggish demand and major overcapacity in many industries. In the absence of sufficient domestic demand, the production may be directed into exports increasing the global supply glut and creating deflationary pressures.
Progress on shifting the emphasis to domestic consumption has been disappointing. Government incentives, in the form of rebates for purchases of high value durables such as cars and white goods, have increased consumption (up 15% from 2008). But, over the last 25 years, Chinese consumption has declined from around 50% to its current levels of 37%.
The current expansion in lending also risks creating China's own homegrown banking crisis with a rise in non-performing bank loans. The problems of bad debts from loose lending are not new. In the 1990s, similar credit expansion led to an increase in bad debts. The big state-owned Chinese banks had to be substantially recapitalized and restructured at significant cost to the State in a series of steps that ended as recently as 2004.
Chinese bank regulators are concerned that new lending is being used to finance real estate and stock market speculation rather than productive purposes. They have moved to try to reduce speculative lending, but it is likely that the central bank will resolutely maintain its moderately loose monetary policy because of uncertainties in the external and domestic environment.
On August 24, 2009, Chinese Premier Wen Jiabao was reported as saying: "China will maintain its stimulative policy stance because the economy, far from being on solid footing, is facing fresh difficulties ….''
There are also concerns that Chinese statistics are unreliable and frequently manipulated by officials to meet political and personal objectives. One unexplained and nagging discrepancy is the difference between reported growth figures and electricity consumption. It is difficult to reconcile falls in electricity consumption with continued robust economic growth.
Even China's state-controlled media has become increasingly skeptical about the accuracy of statistics. In recent polls, a high percentage of the population doubted official data.
International commentators have become concerned about the quality of the economic data. Commenting on the time taken by China's National Bureau of Statistics (NBS) to compile growth data, Derek Scissors, from the Washington-based Heritage Foundation, wryly observed: "Despite starkly limited resources and a dynamic, complex economy, the state statistical bureau again needed only 15 days to survey the economic progress of 1.3 billion people."
The problems extend to financial information as generally accepted accounting principles are not generally accepted in China. Writing in the August 17, 2009, New York Times, Mark Dixon, a mergers and acquisition advisor in China, expressed surprise that revenue and cost gymnastics were not included as an official event at the Beijing Olympics.
Bounding Mines
China's $2 trillion foreign currency reserves, a large proportion denominated in dollars, may have limited value. They cannot be liquidated or mobilized without massive losses because of their sheer size. Increasingly strident Chinese rhetoric reflects rising concern about the security of these dollar investments as the United States issues massive amounts of debt reducing the value of Treasury bonds and the currency.
"If anything goes wrong in the U.S. financial sector, we are anxious about the safety and security of Chinese capital," China's Premier Wen Jiabao has said. Yu Yindong, a former adviser to the Chinese central bank, has castigated the United States over its "reckless policies." He asked U.S. Treasury Secretary Timothy Geithner to "show us some arithmetic." At the University of Beijing, Mr. Geithner obliged, indicating that the U.S. intended to reduce its budget deficit to 3% of GDP from its current level of 12%, eliciting sceptical laughter from students.
China's position is similar to that of a bank or investor with poor quality assets. China is trying to switch its reserves into real assets – commodities or resource producers where foreign countries will allow.
In the meantime, China continues to purchase more dollars and U.S. Treasury bonds to preserve the value of existing holdings in a surreal logic. On the other side, the United States continues to seek to preserve the status of the dollar as the sole reserve currency in order to enable the Treasury to finance America's budget and trade deficit.
Every lender knows Keynes' famous observation: "If I owe you a pound, I have a problem; but if I owe you a million, the problem is yours." Almost 40 years ago, then-U.S. Treasury Secretary John Connally accurately identified China's problem: "it may be our currency, but it's your problem."
China's position is like that of an unfortunate who has stepped on a type of anti-personnel mine, known as a bounding mine. The mine does not explode when you step on it. Instead, it trips when you step off it as a small charge propels the body of the mine into the air where the explosive charge bursts and sprays fragmentation. China, in building and investing its massive foreign exchange reserves in dollars and U.S. Treasury Bonds, has stepped onto the mine and it cannot step off without serious damage!
The Future That Was
China's economic model is reminiscent of 17th century mercantilist policies. Thomas Mun, a director of the East India Company, wrote that the purpose of trade was to export more than you imported. At the same time, a country should amass foreign ‘treasure' that would be the basis of acquiring foreign colonies to allow control of essential natural resources. The strategy required reducing domestic consumption and imports and export of goods manufactured with imported foreign raw materials. China's strategy coincides almost entirely with Mun's views.
China's mercantilist strategies have important implications for other developing countries. Chinese investment in and trade with Latin America and Africa is concentrated on securing access to resources, forcing these nations to specialize in commodities. This reversion to a 19th century trend may not be compatible with Latin American and African long-term development and stability.
The Chinese economic model may be unsustainable. It relies on global trade and investment (much of it export related), which together contribute a high proportion of China's GDP. This trade entails importing foreign components that are then reassembled and then exported. Domestic consumption has been kept low. Treasure has been built up in the form of domestic savings and trade surpluses.
Recently, China announced that its $2 trillion treasure would be used to make foreign acquisitions to secure exclusive access to raw material. The problem is that China's treasure is already invested in assets of dubious value and limited liquidity to finance global consumption.
Chinese Premier Wen Jiabao warned that the Chinese growth was becoming increasingly "unstable, unbalanced, uncoordinated and ultimately unsustainable." That was two years ago! There is broad agreement that a key component of the GFC was the problem of global capital imbalances. A central feature was debt-funded consumption by the United States that allowed 5% of the global population to constitute 25% of its GDP, 15% of consumption and 48% of global current account deficit. Japan, China, Germany and the other savers funded the consumption.
Any lasting solution to the GFC requires this imbalance to be dealt with. The glib solution requires the United States to save more and consume less and the savers to save less and consume more. The problems in implementing the solution are considerable. Timothy Geithner's recent discussion with Chinese officials, to assure his hosts of the safety of their investments in dollars and U.S. Treasury Bonds, reveals the dilemma.
On the one hand, America needs the Chinese to continue and increase their purchase of U.S. government debt to finance its fiscal stimulus and bailouts. On the other hand, America needs China to cut the size of its current account surplus, boost government spending, encourage personal consumption and reduce savings. All this should also occur ideally without any major decline in the value of the dollar or U.S. Treasury bonds or the need for China to liberalize its currency and allow internationalization of the Renminbi.
A cursory look at the respective economies also highlights the magnitude of the task. Consumption's contribution to U.S. GDP is 71%, while in China it is 37%. Given that the GDP of China is around $4 trillion to $5 trillion versus the U.S.'s $15 trillion, and that the average income in China is 10% to 15% of U.S. earnings, the difficulty of using Chinese consumption to drive the global economy becomes apparent.
During the last quarter of century, Chinese savings have risen and exports have been the engine for growth. Given that a significant portion of exports is driven ultimately by American and European buyers, lower global growth and declining consumption creates significant challenges for China.
Dealing with the global imbalance has not been a high priority in the various summits global leaders have shuttled to and from.
In March 2009, in advance of a scheduled G-20 meeting, the Chinese central bank proposed replacing the U.S. dollar as the international reserve currency with a new global system controlled by the International Monetary Fund The United States predictably dismissed the proposal, and The Wall Street Journal argued that, "for all its faults, the dollar is attractive as a reserve currency because it is the common language of global finance and trade. In other words, its appeal is proportionate to how many other market players use it. The unstated reason was the loss of the ability to finance itself in its own currency would significantly disadvantage the US.
In July, 2009, at the G88 Summit in the earthquake-damaged town of L'Aquila in Italy, Dai Bingguo, Chinese state councillor, was again openly critical of the dominant role of the U.S. dollar as a global reserve currency. "We should have a better system for reserve currency issuance and regulation, so that we can maintain relative stability of major reserve currencies exchange rates and promote a diversified and rational international reserve currency system."
Western leaders expressed concerns about even raising the issue, fearing that discussion of long-term currency issues could undermine the nascent recovery in markets and economies.
In September 2009, the Americans and Europeans proposed an effort to tackle global economic imbalances at the G-20 summit in Pittsburgh. Against a background of rising trade tensions, China's ambassador to the United States, Zhou Wenzhong, expressed scepticism about the proposals, seeking focus instead on avoiding protectionism.
Still heavily reliant on exports, China was wary of a global push on imbalances that would focus on its large trade surplus (which reached nearly 10 per cent of GDP in 2008). Zhou pointedly blamed the crisis on "the lack of supervision and abuse of the openness of the market, very risky levels of leverage and too much speculation." He proposed improving global financial supervision, strengthening bank capital and creating global early warning systems to identify threats, but resisted action to address the imbalance.
Ironically, recent modest improvements in the global economy potentially risk increasing the same imbalances that were one of the factors that caused the current financial crisis.
Turning Japanese
China's problems, to a degree, mirror earlier problems of Japan, its neighbor and competitor for global influence.
Japan's export driven model successfully generated strong growth of 10% average in the 1960s, 5% in the 1970s and 4% in the 1980s. This growth was driven by a number of factors, including an artificially low exchange Yen rate.
On September 22, 1985, Japan, the United States, the U. K., Germany and France signed the Plaza Accord, agreeing to depreciate the dollar in relation to the Japanese Yen and German Deutsche Mark by intervention in currency markets. The Accord had limited success in reducing the U.S. trade deficit or helping the American economy out of recession.
The Plaza Accord signaled Japan's emergence as an important participant in the international monetary system and global economy. The effects on the Japanese economy were disastrous.
The stronger Yen triggered a recession in Japan's export-dependent economy. In an effort to restart the economy, Japan pursued expansionary monetary policies that led to the Japanese asset price bubble that collapsed in 1989. Economic growth fell sharply and Japan entered an extended period of lower growth and recession, generally referred to as "The Lost Decade."
In the 1990s, Japan ran massive budget deficits to finance large public works programs in a largely unsuccessful attempt to stimulate growth to end the economy's stagnation. Only structural reforms in the late 1990s and early 2000s restored modest rates of growth. Japan's public debt is now approaching 200% of Japan's GDP.
Significant shifts in economic strategy are now necessary. Chinese President Hu Jintao recently noted: "From a long-term perspective, it is necessary to change those models of economic growth that are not sustainable and to address the underlying problems in member economies."
China can try to continue its existing economic strategy, which looks increasingly difficult. Changing its economic model is also difficult if it means a slower rate of growth. China's challenge will be to learn from and avoid the problems and fate of Japan.
History and cultural issues compound China's dilemma. The 1842 Treaty of Nanking entered into at the end of the first Opium War awarded Britain war reparations, eliminated the Chinese Hong monopoly, set Chinese exports and imports at a low rate, provided British access to several Chinese ports and transferred Hong Kong to the English. The humiliation of the Treaty is deeply etched into China's dealing with the West.
China should have heeded the warning of Kang His, emperor of China, on the British presence at Canton in 1717: "There is cause for apprehension lest in centuries or millennia to come China may be endangered by collision with the nations of the West."
The tradeoff between economic and political liberalization may also be problematic. As Fang Li, a renowned astro-physicist often called China's Andrei Sakharov, remarks in dissident author Ma Jian's novel about China "Beijing Coma": "Without a democratic political system in place, [China's] economy will eventually flounder. The people's wealth will be eaten up by the corrupt institutions of this one party state."
There is an apocryphal story about a visiting world leader drawing back the current of his hotel room to be stunned by the futuristic skyline of Shanghai's Pudong Financial District. "How long has this being going on?" he asked. Today, the question might be:
"How long can this go on?"
Satyajit Das is a risk consultant and author of "Traders, Guns & Money: Knowns and Unknowns in the Dazzling World of Derivatives" (2006, FT-Prentice Hall).
Thursday, February 18, 2010

Thursday, February 11, 2010
But Ben, A Bubble Has No National Boundaries...
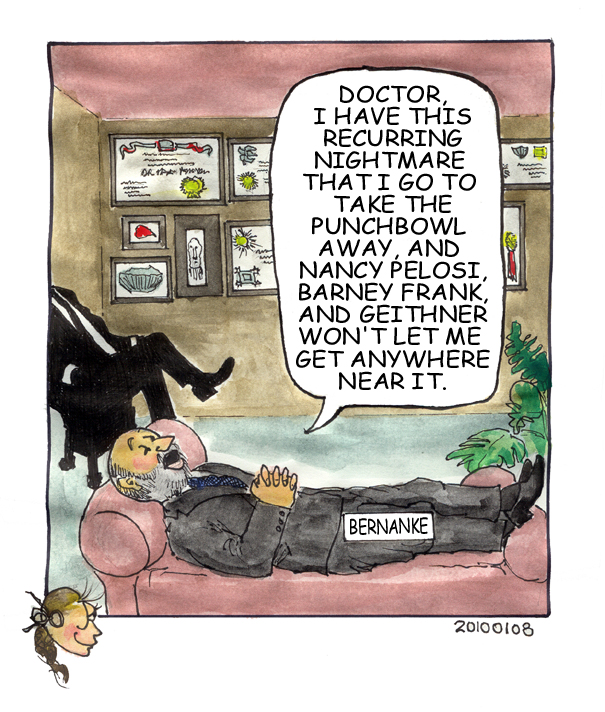
But Ben, A Bubble Has No National Boundaries
Ben Bernanke is showing himself to be more of a Big-Government politician than a scientist. In his latest speech, he has tried to defend the actions of his predecessors by claiming that their easy-money monetary policy only holds five percent of the responsibility for the high real estate prices that ignited the boom-and-bust bubble that almost broke the back of the global economy.
According to his analysis, 30 percent of the responsibility goes to what he has been calling the "global savings glut." The other 65 percent, he says, belongs to the inferior standards of the US mortgage market. Therefore, his argument seems to be saying that if we cure the standards we cure the problem.
He attempts to prove his point by demonstrating through charts that other countries had even looser monetary policy than the US, and yet they did not show a worse real estate boom; therefore, he concludes, loose monetary policy does not cause bubbles.
This sounds convincing, coming as it does from the highest-placed economic academician in the land. But his logic is flawed.
There are two problems with his argument. First, you cannot isolate these particular variables as he has done. To do so is the equivalent of saying Michael Phelps eats a lot, and he is not obese, therefore a high-calorie diet does not cause obesity. (Michael Phelps is the Olympic medalist swimmer who purportedly eats around 8,000-10,000 calories a day. A scientist could probably prove that he also spends almost 8,000-10,000 calories a day in his sports activities.)
Second, although Bernanke seems to accept the wisdom that a nation's monetary looseness can create excess purchasing media that can then chase relatively fewer goods, he doesn't seem to admit that there is no economic law that restricts a purchasing media's use to its country of origin, at least not in an immediate temporal sense.
Although US dollars must ultimately come to roost back in the US, they may station themselves in any number of places for many years (to wit, China's Current Account Surplus, for example) before they find their way here; and while so stashed, they can be used as collateral for any number of ventures in the meantime, in any currency--say, for example, to buy Spanish pesetas to be invested in Spain's real estate boom.
By the same token, a loose yen, for example, can go on a bubble-blowing spending binge in the US through the carry trade (borrowing in yen to obtain dollar-denominated instruments, or even cash dollars).
Bernanke's effort is a perfect example of the econometrician's Achilles Heel: narrow-sightedness. Markets are fluid, complicated, convoluted, multifaceted mishmashes of changing signals and events. For his analysis to work it must include a variable for each relevant event, not just an isolated one or two.
I find it strange that high-powered government officials feel justified in using such flawed science to defend themselves, even if they were to claim they do it for some lofty cause like the preservation of market confidence.
Labels: Bernanke, econometrics, housing bubble, monetary policy
Tuesday, February 02, 2010
Let’s atomize Wall Street...
Let’s atomize Wall Street, by Martin Hutchinson
Paul Volcker’s proposal that proprietary trading should be spun off from deposit-taking banks is a worthwhile step in the direction of stabilizing the financial services business. However, when you consider that business in detail, it becomes clear that further breakups are necessary in order to remove the excessive risks from the U.S. economic system.
Volcker became something of a hero to the left for his sponsorship of President Obama’s bank-bashing announcement. Indeed, I was very much hoping that he could ride this new-found enthusiasm through a defeat of Ben Bernanke in his Senate confirmation vote, followed by a more or less unanimous Senate approval of a Volcker nomination to replace him as Fed chairman. Assuming Volcker hadn’t suffered a Damascene conversion to sloppy monetary policy while I wasn’t looking, Obama and the left would be suffering buyer’s remorse within about an hour of Volcker’s arrival at the Fed, but by that stage the deed would be done. I was practicing my Dr. Evil laugh for this eventuality, but alas it was not to be.
There are three problems with the current setup on Wall Street: systemic risk, rent seeking and conflicts of interest. The Volcker proposal addresses the systemic risk problem to a great extent, but does not do much about the other two. For a complete solution, we thus need to go further.
When Treasury Secretary Larry Summers and former Senator Phil Gramm (R-Texas), among others, pushed through repeal of the Glass-Steagall Act in 1999, they didn’t give proper thought to the dangers of institutions funding a traders’ casino with guaranteed deposits. The introduction of Glass-Steagall in 1934 had been highly damaging to the economy, because it decapitalized the investment banks, killing off the capital markets for the remainder of the 1930s and playing a major role in prolonging the Great Depression. However, by 1999, the investment banks were more than adequately capitalized (provided they followed sound principles of risk management and leverage, which of course they increasingly didn’t). Thus, the rationale for allowing commercial banking and investment banking to be combined was shaky at best. It should have caused further doubt that the trigger for Glass-Steagall repeal was the acquisition of the investment bank Salomon Brothers by Citigroup, itself a quagmire of conflicts of interest that had been bailed out from bankruptcy only eight years before.
However, restoring Glass-Steagall as it was would achieve nothing. After all, the two most serious failures of risk management in the 2008 crash were collateralized debt obligations, involving a mortgage bond market in which commercial banks’ securitization operations have always been active, and credit default swaps, a product in which commercial banks were intimately involved from the first. Conventional underwriting of corporate debt and equity securities, the activity prohibited to commercial banks by Glass-Steagall, was not the problem, as it might have been had the crash occurred with the bursting of the 1999 dot-com bubble. The principal risks involved in finance today are those incurred by traders, but those proliferate in both types of banking.
It’s not clear how Volcker’s ban on proprietary trading in banks benefiting from deposit insurance would work. Every bank foreign exchange desk and money desk trades on the bank’s own account in almost every transaction it makes (relatively few transactions are pure brokerage between two counterparties.) Thus, however simple the bank’s operations, it cannot avoid “proprietary trading.” Of course you can ban separate “prop trading” desks, but in a naughty world that would drive the proprietary traders to integrate themselves into the operations of the various products concerned, thus negating the effect of the legislation.
The other problem with the Volcker proposal is that even without separate proprietary trading operations, the banks are undertaking risks which they don’t manage properly. Wall Street risk management systems are based on assumptions of Gaussian randomness in markets that are demonstrably far from realistic. In particular, Wall Street risk management systems understate the risk of several highly risky products such as collateralized debt obligations and credit default swaps. This understatement is in the interest of bank management, which benefits from state bailouts when it all goes wrong. It is even more in the interest of traders, who by and large make the most money from trading the riskiest instruments, and hence welcome artificially large position limits for those instruments. Since current Wall Street risk management methods are in the interest of those who work on Wall Street, they will not be changed except by regulatory means. Before their alteration they will, even without proprietary trading, leave the Wall Street behemoths in continual danger of explosion.
Rent-seeking is another current problem of Wall Street, not addressed by Volcker. This takes many forms, and has resulted from computerization and from the endless proliferation of derivative instruments. Basically, Wall Street houses, by their substantial market share in trading businesses, acquire insider information about money flows, and then profit by trading on this information. Traders have always done this, of course, and there is no sensible way of making it illegal. In addition genuine “crony capitalism” insider information about future finances and future government actions is as available as it always has been, but with larger trading volumes and fewer inhibitions is more usable without technically contravening insider treading legislation. Thus insider trading, almost all of it technically legal, has acquired an enormously magnified profit potential. This is the principal reason for Wall Street’s greater share of the economy; the genuine value added to third parties from “hedging” or liquidity” is only a tiny fraction of the rents Wall Street can extract from these markets.
There is no complete solution to this problem, but the best palliative is a “Tobin tax,” a modest ad valorem transaction tax on each trade. By this means, the profitability of “high speed trading” would be eliminated and many of the other insider trading strategies would be reduced in scope and profitability, particularly if the tax were levied on the nominal principal amount of a derivative and not on its theoretical value. This would in turn swing the power base within Wall Street away from traders and back towards bankers and corporate financiers, whose approach to life is more conducive to maximizing those houses’ genuine economic value added.
The final problem in the Wall Street behemoths, that of conflicts of interest, requires no legislative solution, at least as far as the corporate customers are concerned, but only that the financing business remain adequately competitive. With behemoths doing corporate financing transactions, any of their customers is faced with huge conflicts in dealing with them. If a company provides them with sensitive corporate data, it may be subjected to a leveraged buyout. If a company entrusts them with a new financing, it may find their trading operation shorting it, either directly or indirectly. (Those mortgage originators and investors still in business, for example, can reasonably feel miffed with Goldman Sachs making a profit from shorting subprime mortgage bonds through the CDS market while it was at the same time issuing and selling new ones). Wall Street pretends to operate internal “Chinese walls” through which sensitive information does not penetrate, but to rely on those is to put yourself entirely under the protection of Wall Street’s ethical integrity, a security currently trading at a very substantial discount.
The solution to these conflicts of interest is “single capacity,” the system under which the City of London acted until the passage of the Financial Services Act of 1986, surely among the most misguided legislation in human history. Under this system brokers, who sold securities, were kept separate from jobbers, who made markets in them. Both were separate from merchant bankers who arranged financings and carried out mergers and acquisition transactions. When an underwriting took place, the merchant bank arranged the transaction and the brokers sold the underwriting to insurance companies and other large investment institutions, who earned additional income by backstopping deals in this way. “Proprietary trading” was undertaken by investment trusts, pools of money whose business was to maximize income for their investors, in a similar way to a U.S. hedge fund. As for banking, that was done by the merchant banks if complicated, but the high volume simple transactions were carried out by the clearing banks, home of the nation’s retail deposits but not known for their intellectual heavy lifting.
It worked beautifully, just as well as the modern system, indeed better. It cost far less, in terms of the wealth it extracted from the economy. It was much less risky. And there were few conflicts of interest; each participant in the business, having only one function and capability, was devoted to its own interest rather than torn between the interests of several participants in every transaction.
This system is to some extent returning anyway, with the increasing market share of “boutique” investment banks such as Greenhill & Co. and Evercore Partners, which at least have fewer conflicts of interest than the behemoths. However, a regulatory “nudge” or two would be no bad thing.
As I said, Volcker had a good idea, but he did not go nearly far enough.
The Bears Lair is a weekly column that is intended to appear each Monday, an appropriately gloomy day of the week. Its rationale is that, in the long ’90s boom, the proportion of “sell” recommendations put out by Wall Street houses declined from 9 percent of all research reports to 1 percent and has only modestly rebounded since. Accordingly, investors have an excess of positive information and very little negative information. The column thus takes the ursine view of life and the market, in the hope that it may be usefully different from what investors see elsewhere.
Martin Hutchinson is the author of “Great Conservatives” (Academica Press, 2005). Details can be found on the Web site www.greatconservatives.com.
Friday, January 22, 2010
EMH Funeral Oration...
EMH Funeral Oration, by Satyajit Das
Like Mark Anthony with Julius Caesar, many have now come to bury the Efficient Market Hypothesis (”EMH”) rather than praise it. Amusingly, some of the critics who have recently found their voice are those who for years made their living from financial markets that were predicated in no small measure from the intellectual dogmas that EMH was central to.
In his previous book Dot.Con, John Cassidy, a writer for the New Yorker, provided a penetrating history of the Internet bubble and its bust. In How Markets Fail, Mr. Cassidy attempts a critique of modern economics. In this regard, he covers similar ground to Justin Fox’s The Myth of the Rational Market and Pablo Triana’s Lecturing Birds on Flying.
At its best, How Markets Fail provides a vivid history of recent economic thought and its influence on events that laid the foundations of the global financial crisis. Drawing on anecdotes and interviews, Mr. Cassidy provides an accurate outline of the developmental trajectory of modern economies.
His description of a noted confrontation between Raghuram G. Rajan and orthodox economists led by Larry Summers and members of the Fed, at a Jackson Hole meeting is revealing. Rajan, then the chief economist of the International Monetary Fund, warned about the risks embedded in the financial system. His detractors blithely denigrated the concerns on ideological grounds.
Mr.Cassidy also attempts to extend the text to encompass a critical review of what he calls “Utopian Economics”. The central focus of the criticism is that society is best served by individual self-interest and free markets. Mr. Cassidy’s argument is that individual self interest does not work, markets frequently fail, price mechanisms are flawed and markets are plagued by problems of information asymmetry – different levels of knowledge between participants.
In his criticisms, How Markets Fail is perhaps a little too eager to embrace behavioural economics and the work of Hyman Minsky. Useful as both alternatives are, they are also incomplete explanations of the complex economic and financial relationships.
In the final section of the book argues that it was these failures that led to the disastrous sequence of events that caused the global financial crisis.
Well written and researched, How Markets Fail is superior to the growing list of titles that cover similar ground. Mr. Cassidy largely succeeds in his objectives although the book does not extend the debate. The book undoubtedly will introduce a new generation of readers to the debate and encourage further debate.
There are some contentious and erroneous pieces of analysis of individual technical elements of the theory. In this regard, Donald Mackenzie’s brilliant An Engine Not A Camera provides a more technical and deeper analysis of aspects of the theory.
Recent criticism of the EMH, Chicago economics and “free market idolatry” tends to gloss over some interesting anomalies. Markets are rarely entirely free and regulatory failures were a contributing factor to many of the problems that have emerged. That is not to make the case for unfettered ‘red tooth and claw’ capitalism but to point out that many proposed regulatory interventions will not necessarily have the intended effects.
All economics is deeply embedded in a political, cultural and sociological framework. In many ways, it is symptomatic of these underlying issues.
For example, the analysis of sub-prime mortgages misses several factors. Firstly, a lack of growth in real income, especially for middle and lower paid employees, made it difficult for them to achieve the material success that was daily sold to them by the media and advertising. Secondly, the rise of stated income and low or no documentation mortgage reflected the change in work practice where large parts of the work force were no longer employed full-time. Casual or part-time employment and contracting arrangements made the required proof of income difficult.
Interestingly, many problems arise from the lack of humility about the theories. They are, at best, incomplete and highly conditional models that compare unfavourably to middle-age medical and religious superstitions.
Robert Merton articulated this concept precisely. “At times we can lose sight of the ultimate purpose of the models when their mathematics become too interesting. The mathematics of models can be applied precisely, but the models are not at all precise in their application to the complex real world. Their accuracy as useful approximations to that world varies significantly across time and place. The models should be applied in practice only tentatively, with careful assessment of their limitations in each approximation.” Ironically, the speech was less than a year before the collapse of LTCM. Writing in 1995, Merton foreshadowed the events that were to unfold 3 years later at LTCM: “any virtue can become a vice if taken to extreme”.
As recent events in Copenhagen suggest, the only thing that history tells us is that mankind generally are poor learners. Mr. Cassidy quotes a recent column by Harvard’s Greg Mankiw: “despite the enormity of recent events, the principles of economics are largely unchanged.” Professor Mankiw suggested that student still needed to learn about “the efficiency properties of market outcomes.”
How Markets Fail is perhaps merely a sub-set of a wider phenomenon – How Mankind Fails.
Wednesday, January 20, 2010
Paul Davidson Comments To Posner Article...
I am pleased that Posner has read what I (Davidson) wrote. Yes P{osner is correct that I have used Keynes as the basis for my analysis of uncertainty and Post Keynesian theory. When Keynes wrote, unfortunately, the theory of stochastic probability theory [ ergodic theory] had not been developed in the English language. Thus Keynes’s uncertainty is not terchnically defined and can easily be thought to be the same of Knight’s concept of uncertainty – but they are quite different. Knight is using an epistemological definition of uncertainty, Keynes has an ontological uncertainty concept. This makes a big difference in understanding how financial institutions and money contracts, especially loan contracts i.e., leverage making contracts, affect financial crisis. What I have done was to use technical language to show Keynes’s general theory rejects several axioms that underlie classical theory. The Classical theory's ergodic axiom underlies Friedman’s monetarism, Lucas’s rational expectations, , andthe laissez-faire economic philosophy Fama’s efficient market theory. An axiom is defined as a universal truth that needs not be proven.The ergodic axiom presumes that the same probability distribution that governed past economic outcomes governs all future outcomes. Thus, given the ergodic axiom, the future is statistically predictable– and rational decision makers know (in the actuarial sense at least) what the future is when they make a decision today. Thus, a rational economic person would never sign a loan contract unless he/she “knew” they could service this debt within their known future income and budget constraints. In a classical theory, there can never be a default by optimizing rational people, there can be no foreclosures, and no insolvencies. Hence the theories based on the ergodic axiom cannot develop a useful policy to solve these financial systemic problems when they occur in the world of experience. Keynes rejected the ergodic axiom as a basis for his general theory. Thus, in his general theory, there need not exist any current objective probability distribution that decision makers “know” will govern future outcomes. Without going into details, Knight’s unique events that cause uncertainty is the equivalent of Taleb’s black swan – an occurrence that occurs in an ergodic system but that will have a very low, but still fixed probability , of occurrence. So with a big enough sample one can predict the existence of a black swan financial disaster in a Knight system. In a nonergodic system there is no probability (as Keynes stated in his 1937 article) on which to estimate future outcomes. Thus the necessity to seal economic transaction with monetary contracts that FIX payments into the future!
Read more: http://www.newyorker.com/online/blogs/johncassidy/2010/01/interview-with-richard-posner.html#ixzz0dBN5g3Hs
Read more: http://www.newyorker.com/online/blogs/johncassidy/2010/01/interview-with-richard-posner.html#ixzz0dBN5g3Hs
Friday, January 15, 2010
Everyone Wants to Talk about Currencies...
Everyone Wants to Talk about Currencies
Michael Pettis Jan 11, 2010 4:44PM For now I suspect everyone will want to discuss currencies. One of the more interesting pieces of news for me was yesterday’s Financial Times story on President Sarkozy’s finding “unacceptable” the disordered currency markets (“disorder” means a rising euro). According to the article:
Nicolas Sarkozy on Thursday stepped up his attack on global exchange rate imbalances saying “monetary disorder” had become “unacceptable”. The French president said he would make exchange rate policy an important theme of France’s presidency of the G8 and G20 forums of advanced and developing economies in 2011.
“There cannot be financial, economic and social order until we put an end to currency disorder,” he said at a conference in Paris. Mr Sarkozy has long railed against Chinese “monetary dumping” and the dominance of the dollar, but has sharpened his criticism in recent days reflecting concern in Paris that a balanced economic recovery in the eurozone could be choked off by an overvalued currency.
With a large trade deficit and with exports that are more price-sensitive than Germany’s, France feels more susceptible to exchange-rate movements than its neighbour across the Rhine. “We can’t increase the competitiveness of our businesses in Europe and have the dollar lose 50 per cent of its value against the euro,” Mr Sarkozy said. “When we produce in the eurozone and sell in the dollar zone, are we supposed to just give up selling?”
So we are sort of stuck, aren’t we? The dollar is overvalued, and it must rebalance downwards in order to force up US savings rates relative to US GDP, but since it cannot decline against Asian currencies, whose central banks intervene heavily, it must decline against the floating currencies like the euro.
But the euro is probably already overvalued against the dollar, so European manufacturers will be forced to accept the brunt of the adjustment. This will be painful for everyone in Europe, but I suspect it will be most painful for Germany, a country that is more dependent on manufacturing than the rest of the region and so who will suffer more if there is a sharp drop in demand for European manufactured goods. The fact that President Sarkozy is nonetheless making the most noise about the euro indicates that this is going to become a very popular political topic and has great demagogic appeal.
Later in the article Sarkozy was quoted as saying “You know how close I feel to the US. But this is not possible. The world has become multipolar. We must have a multi-monetary system.” As a half-French half-American I have to say I suspect that it is not likely to be easy to convince too many Americans of the truth of the first part of his statement. I think however, that although the US and the world (except perhaps export-dependent Asian countries) would be better off with a multi-monetary system, Sarkozy may be confusing issues.
The dominance of the dollar in reserve accumulation has little to do with a lack of an alternative currency and a lot to do with the inability of any country but the US to absorb the trade deficits created by export-dependent development strategies. Trade-surplus countries buy dollars because when they buy euros, they cause angry reactions from European businessmen and politicians who are uncomfortable with the impact of a rising euro on domestic manufacturing and employment. In fact, the rise of the euro against the dollar is precisely what Sarkozy claims to oppose in the first part of his statement and to support in the second part. If Asian central banks rely less on the dollar and more on the euro for their reserve accumulation, guess what will happen. Yes, the euro will rise against the dollar.
Japan is worried too
It always surprises me how readily people believe that the status of the dollar as a reserve currency has to do with same nefarious conspiracy. As long as the US is willing and able to run large trade deficits, the dollar will be the overwhelming currency of choice for reserve accumulation. Once the US ability or willingness stops, which I suspect is likely to be the case over the next few years, central banks will stop accumulating dollars. Like it did during the period of large US deficits in the 1960s and the 1980s, the talk about dollar hegemony will once again fade away as US trade deficits decline.
Sarkozy’s comments were reinforced, in a way, by comments the same day from Naoto Kan, Japan’s finance minister. Here is what the South China Morning Post said in an article today.
Japan’s new finance minister backed off his call for a weaker yen following an apparent rebuke from the prime minister yesterday, saying currency levels should be determined by markets.
Still, Naoto Kan said the government should pay heed to the views of the country’s business community, signalling that he was sticking to the view of favouring a weaker yen to boost the competitiveness of Japanese exports. ”Currencies undoubtedly should be determined by markets,” Kan said. “But I also believe that generally speaking, it’s the finance minister’s job to act against currency moves when needed.”
…He jolted markets in his first press briefing as finance minister on Thursday, saying he hoped the yen would weaken further and that he would work with the Bank of Japan to achieve an appropriate exchange rate level.
For those who remember the 1980s, when many policymakers in Japan insisted that Japan’s trade surplus had nothing to do with the value of the currency, and everything to do with domestic competitive advantages in manufacturing, it is a little weird seeing them now worry so much about the impact of a rising yen on their manufacturing sector and on the process of economic recovery. Currencies do matter, I guess.
Currency talk is likely to be the flavor of this year. The currency issue simply will not go away, and the fighting over it is likely to get worse, not better. On that topic, a research fellow at the Institute of World Economics and Politics at CASS had an interesting proposal earlier this week. According to an article in Bloomberg:
China should consider a one-time appreciation in the yuan of 10 percent against the dollar to reduce inflows of speculative capital into China, a researcher at the Chinese Academy of Social Sciences said. The revaluation could be followed by a cap of 3 percent in annual moves up or down for the currency against the greenback, Zhang Bin, a research fellow at the Institute of World Economics and Politics at CASS, which advises the cabinet, said in an interview from Beijing today. He said he couldn’t predict whether his proposal, outlined in an essay, would be adopted by the government.
China may see “huge” inflows of so-called hot money as foreign investors step up bets on yuan gains, Zhang Xiaoqiang, deputy head of the National Development and Reform Commission, said in a statement yesterday. The government has rebuffed calls from U.S. and European officials to allow the market to set the exchange rate and has pegged the yuan at about 6.83 per dollar since July 2008 to help exporters weather a global recession.
“It’s a good strategy to protect China from the impact of short-term capital inflows,” said Zhang. “Now is a very good time. Foreign pressure will intensify this year and China should take an active strategy.”
…A 10 percent revaluation would have limited impact on exports and slow growth in overseas sales by 3.3 percent, said Zhang. Exports dropped 1.2 percent in November from a year earlier, following a 13.8 percent decline the previous month. China’s customs bureau is scheduled to report trade figures for December sometime between Jan. 12 and 14.
Zhang, who has been interviewed by Xinhua news agency on global economics previously, said the revaluation should be adopted soon. “The earlier, the better,” said Zhang. “We shouldn’t wait until after foreign capital flows into China and expectations on yuan gains increase.”
Does the value of the RMB matter for trade?
What would the impact on trade be? Strangely enough many of the opponents of RMB revaluation insist that it would have no impact on trade balances. A new “International Finance Discussion Paper” (Board of Governors of the Federal Reserve System) by Shaghil Ahmed sees it differently (“Are Chinese Exports Sensitive to Changes in the Exchange Rate?”)
The main results of the paper can be summarized as follows: First, including the latest period of greater real exchange rate variability reinforces the conclusions of some earlier studies, such as Marquez and Schindler (2007), which found that Chinese exports respond quite strongly to movements in the real exchange rate, and go against studies which fond little effect of exchange rate changes or effects that go in the opposite direction to conventional wisdom.
Second, considering the components of the real exchange rate, consistent with the theoretical model, when the source of Chinese real exchange rate appreciation is movements of the RMB against other emerging Asian countries, this does not have a significant effect on Chinese processing exports, but it does have a significant negative effect on Chinese non-processing exports. On the other hand, when the source of the renminbi appreciation is movements against the currencies of non-emerging Asian Chinese trading partners, generally both types of exports go down. Moreover, even though processed exports remain very important for China, increases in non-processed exports have recently accounted for more of the overall increase in exports. Finally, model simulations indicate that the path of total Chinese real exports would have been quite a bit lower if the renminbi had appreciated more in recent years.
Overall, the results suggest that greater exchange rate flexibility could have significant impact on China’s trade balance by restraining growth of exports, particularly non-processed exports.
…The implications of the results for global imbalances depend on what is exactly meant by global imbalances, which is not always clear-cut. If China’s large current account surplus or its bilateral current account surplus with the United States by itself contributes to global imbalances, along with the U.S. bilateral current account deficit with China, then our results suggest that greater degree of appreciation of the Chinese currency would substantially help mitigate global imbalances. If, however, the big part of global imbalances is the U.S. overall current account deficit and the current account surplus of the emerging market world taken together, then it is less clear that greater appreciation of the Chinese currency would make a significant dent to global imbalances. For example, following an adjustment of the Chinese real exchange rate one scenario could well be that the fall in exports by China is largely matched by a rise in exports by other emerging market economies, including in emerging Asia, leaving aggregate current account balances of the United States and of emerging market economies more broadly unchanged.
But the results do seem to imply that greater flexibility of the exchange rate would help China toward its stated desired goal of shifting the sources of growth more toward domestic demand with less dependence on external demand.
Regular readers of my blog might remember that from late 2006 until the beginning of 2008 I had argued that the best way for China to address the domestic (and of course external) problems caused by the undervalued exchange rate would be for a 15-20% one-off revaluation. This would both force through a rebalancing and help revive consumption growth, all the while protecting the country from the problem of hot money inflows, which had become terrible by that time.
After the onset of the crisis I backed away from such a large revaluation (not because it wouldn’t be a good idea in the long run, but rather because it would be too painful in short run) while still arguing that a one-off 10% revaluation still made sense. Needless to say I enthusiastically agree with Zhang Bin although, like him, I am doubtful that policymakers will be willing to absorb the short term cost in exchange for domestic economic benefits that probably won’t accrue until well after 2012, when the current leadership will have retired.
Hot money
My guess is that we will see a much smaller appreciation, perhaps 2-3% during the first quarter. Apparently I am not the only one who believes that appreciation pressures are mounting. That terrible bugbear, which made China’s too-little-too-late appreciation strategy from 2005 to 2008 so difficult for the PBoC, hot money inflows, seems to be rapidly becoming a problem again. Earlier this week a senior policy advisor sounded, and not for the first time, the warning. According to an article in Bloomberg:
China may see “huge” speculative inflows as overseas investors step up bets on yuan gains, making it difficult to manage liquidity, said Zhang Xiaoqiang, deputy head of the nation’s top planning agency. Loose monetary polices in developed countries, a weakening U.S. dollar and China’s economic recovery will put renewed pressure on the yuan to appreciate, Zhang, from the National Development and Reform Commission, said in a statement on its Web site today. The country is becoming more reliant on foreign economies, he said.
Already some of my students whose parents own their own businesses have been telling me that Chinese speculative money held abroad is flowing back into the country. One of my students from rich coastal city Wenzhou, the most free-wheeling and business-savvy city in China, and perhaps the world, just rolled his eyes when I asked him if his family and friends were tying to bring money into the country. “Of course,” he said. I didn’t get the impression that he thought mine was an especially astute question.
Meanwhile all the big guns in the “monetary alarmist” camp in China have been pounding the table (in the discreet way preferred of policymakers here) about the risks of monetary expansion. As everyone now knows, the PBoC yesterday sold three-month bills at a higher interest rate for the first time in 19 weeks. Long Chen, one of the students in my PBoC Shadow Committee seminar, reported to the class via email as soon as it happened: “Hey guys, the primary yield of 3M PBOC bill increased this week. Significant sign.”
Yes, although the increase was tiny, it may indeed be a significant sign that the PBoC no longer wants to wait and is starting to tighten conditions, although I can only add that conditions are so alarmingly loose that it would take an awful lot of tightening to get back just to “loose”, and it would be hard to do this without seriously undermining current growth and employment in the short term. My guess is that this may be a beginning, but it will be a very slow and tentative beginning. The PBoC has already been lambasted (unfairly, in my opinion) for jumping the gun in 2007 and 2008 and they have little political capital against which they can afford another “mistake”.
In fact much of their action tends to be signaling – what in the US we would call “jawboning”. Four days ago, for example, Governor Zhou made another attempt to warn about risks to the banking system in an interview with China Finance very similar to a speech he gave late December. According to an article in Bloomberg:
Chinese central bank Governor Zhou Xiaochuan reiterated government warnings that investment in industries with excess capacity and in redundant infrastructure projects could threaten banks’ loan quality.
The People’s Bank of China will guide credit, seeking to avoid volatility in lending, Zhou said in an interview dated yesterday on the Web site of China Finance, a central bank publication. Investment in duplicated projects or industries with overcapacity could “pose a risk to the quality of banks’ loans,” Zhou said.
China’s policy makers are seeking to contain risks from an unprecedented credit boom, in which banks extended 9.21 trillion yuan ($1.3 trillion) of new loans in the first 11 months of 2009. Liu Mingkang, chairman of the China Banking Regulatory Commission, said yesterday that lenders have “more than” enough capital, while also cautioning that asset bubbles may emerge in the world’s third-biggest economy.
It is hard to be both soothing and at the same time to raise the alarm.
To move away from currencies and monetary policy, I saw an interesting article about the US in Xinhua.
A recent New York Times/CBS News poll has found that more than half of Americans said they are spending less money in stores and online. A New York Times report available on its website Saturday quotes the poll as saying that nearly half of Americans said they were spending less time buying nonessentials.
“Some are working longer hours, but a larger proportion are spending additional time with family and friends, gardening, cooking, reading, watching television and engaging in other hobbies,” says the report. The report also quotes the U.S. Department of Labor’s time-use survey as showing that compared with 2005, Americans spent less time in 2008 buying goods and services and more time cooking or taking part in “organizational, civic and religious activities.”
Net demand from abroad
This is almost certainly good news for the US in the medium term, but if true, needless to say, it seriously undermines hopes that US net demand will revive enough to justify the overcapacity issues exacerbated by China’s fiscal and credit expansion. There has been some hope that boosting trade with developing countries, and especially with developing Asia, will result in a new source of net demand. James Kynge said something like this in the Financial Times earlier this week:
Popular narratives sometimes overshoot. One of the latest to outlast its veracity is the conventional wisdom that China’s export engines have been spiked by subsiding consumer demand in the US. This, so the argument goes, leaves Beijing with no option but to spur domestic demand to compensate for lost export revenues.
This became an über-narrative last year. Its snowballing popular appeal was powered by two unassailable charms: it made sense and seemed largely true – but not any longer. Its potency appears set to wane in coming months not so much because of a challenge to its central plot, but by other things happening off stage.
The telling off-stage action is the recent upsurge in trade with south-east Asia and the “newly-rising economies” of Brazil, Africa and India. Although Chinese trade with these places has historically been limited, it has grown so fast in the past five years that a robust performance in 2010 may be enough to offset any moderate weakness in China’s trade with the US.
A friend wrote to me to ask what I thought of this possibility, citing Kynge’s article, and my response (with some editing) was:
The idea that net demand from developing countries can replace net demand form the US is alarmingly widespread, both in China and abroad, and mainly indicates to me a lack of familiarity with the history of developing countries. The developing world excluding China is roughly the same size as the US, so if you want them to replace the US you need the developing world to run trade deficits of roughly equal to 7% of their GDPs.
Leave aside the huge problem that most developing countries also want trade surpluses and have a stubbornly tough time understanding why they should run deficits in order to help Chinese employment, the historical evidence suggests that just a few years of trade deficits of 2% of GDP will lead to external debt crisis. For example it took the Asian Tigers just a few years of deficits after 1993-94 to run into the Asian crisis. Do Malaysia, Indonesia, Vietnam and so on really want to go through that again? Developing country demand cannot replace the US. Even Europe cannot replace the US. This is an unrealistic hope.
No, I think the rapid growth of US consumption relative to (very healthy) US GDP over the past 30 years or longer may have been a special historical circumstance whose life, if not over, is coming to a close. Except for small countries whose trade surplus can easily be accommodated, I think the days of rapid growth driven by trade-surplus policies may be over.
This is getting to be another of my very long pieces (as my friend Kaiser Kuo reminded me last night at my club), so I will stop, but not before referring to one last interesting article about another controversy in Chinese academic circles. China is trying very hard to boost the quality of its scientific and technological research, which is, with a few exceptions, of very low quality. I am skeptical about how successful they will be, in part because the educational system here, as a history teacher in the top high school in Shanxi province once told me, is a machine for stamping out critical and creative thinking, and in part because the process is not being driven by scientists but by bureaucrats. Here is what the South China Morning Post says:
The exposure of two researchers who published fake data in an international journal is the subject of heated debate in mainland scientific circles, with opinion divided on whether the blame should rest on unscrupulous individual behaviour or deep flaws in the academic system.
Zhong Hua and Liu Tao from Jinggangshan University in Jiangxi published faked datasets in specialist journal Acta Crystallographica Section E in 2007. The fraud would have gone undetected without new computer analysis, the journal said on its website.
Leading British medical journal The Lancet urged China to tighten measures against scientific fraud, otherwise it would not become the research superpower President Hu Jintao has pledged by 2020.
These kinds of problems are so commonplace that normally I wouldn’t bring it up except for two reasons. The first is that it is a measure of how complex the problem is that there is even a debate about this episode. Normally, faking research brings universal condemnation, but the researchers have earned some sympathy because they are desperately responding to a very difficult system. The second reason I cite this article, which follows the first, is because of a very perceptive quote from Professor Jiang Gaoming of the Institute of Botany under the Chinese Academy of Sciences:
“All living creatures have an instinct to survive. When a bad system determines the survival of researchers, they have to do all kinds of corrupt and unethical things to live. The outcome is inevitable,” Jiang wrote.
This is something I often tell my students, especially about the banking system. It is not because they are especially stupid or dishonest that bankers have made bad loans, but rather because they are responding intelligently to bad incentives. Any system with distorted incentives creates distorted results.
--------------------------------------------------------------------------------
Opinions and comments on RGE EconoMonitors do not necessarily reflect the views of Roubini Global Economics, LLC, which encourages a free-ranging debate among its own analysts and our EconoMonitor community. RGE takes no responsibility for verifying the accuracy of any opinions expressed by outside contributors. We encourage cross-linking but must insist that no forwarding, reprinting, republication or any other redistribution of RGE content is permissible without expressed consent of RGE.
Wednesday, January 13, 2010
Scary Statistics...
Here's the scariest statistics you'll ever see. It's the decline in global transactions since last year's numbers__C.H.I.P.S.
Global transactions have shrunk from $508,758,657,298,000 to $364,355,126,940,000 as the difference from Dec 31, 2008 to Dec. 31, 2009... That's a shrinkage of $144 trillion dollars over the year...
What do you really think the outcome is going to be...?
Global derivatives contracts also shrunk from a high of $684 trillion in June 2008 to $592 trillion in Dec. 2008, and the most recent data of June 2009 shows they were at $605 trillion...
I think it's time for the nation and the world to start taking this global financial disaster much more seriously, than they are pretending to__What do you think...?
Wednesday, December 30, 2009
TIME FOR A NEW “NEW DEAL”
This is an older article by Marshall Auerback, but one of the best about what was done by FDR, and what should now be done.
But consider the historic precedents. In the words of Professor Paul Davidson:
Let us look at a historical example where if this type of “what will cost to the tax payer and/or the economy?” question were asked, one of the most desirable government policies would never have been undertaken. At the Bretton Woods conference it was recognized that the European nations would need significant aid to help rebuild their economies after the war. Keynes estimated that the need would be between $12 and $15 billion. U.S. representative Harry Dexter White indicated that Congress could not ask the taxpayers to provide more than $3 billion. Accordingly, the Keynes Plan was defeated at Bretton Woods, and the Dexter White proposals were adopted:
Suppose that in 1946 it was recommended that U.S. give a gift of $13 billion dollars over four years to various European countries to help them rebuild their war-ravaged economies (in 1940s current dollars, this sum would be well over $150 billion in 2007 dollars). Obviously if Dexter White was correct, the Congress would never have approved the Marshall Plan. Since the Marshall Plan did not reveal in advance that it would provide foreign governments $13 billion over a period of four years, Congress approved the Marshall Pan. The Marshall Plan gave foreign nations approximately two percent of the United States’ GDP each year for four years. Was the Marshall Plan costly to U.S. taxpayers and the U.S. economy?
The statistics indicate that, during the Marshall Plan years, for the first time in history the U.S. did not experience a serious economic slowdown immediately after a war. And this despite the fact that federal government expenditures on goods and services declined by approximately 57 percent between 1945 and 1946. Furthermore, four years after World War II, federal government expenditure was still approximately half of what it had been in 1945.
When the U.S. emerged from World War II, the federal debt was more than 100 percent of the GDP. Accordingly, there was great political pressure to reign in federal government spending to make sure that the federal debt did not grow substantially. Clearly, then, it was not “Keynesian” deficit spending that kept the U.S. out of recession in the immediate post-World War II years.
What was the cost of the Marshall Plan to the U.S. economy and the U.S. taxpayer? In 1946, the GDP per capita was 25 percent higher than it had been in the last peace years before the War. GDP per capita continued to grow during the Marshall Plan years. Despite giving away two percent of U.S. GDP, American residents (and taxpayers) experienced a higher standard of living each year. – (Paul Davidson, “How to Solve the US Housing Problem and Avoid a Recession: A Revived HOLC and RTC” - Schwartz Center For Economic Policy Analysis: Policy Note, January 2008)
(Continue...)
Saturday, December 19, 2009
The recession is over but the depression has just begun...
Edward Harrison here. This is an updated version of a post I wrote about two-and-a-half months ago over at Credit Writedowns. When I wrote it, I had been looking for bullish data points as counterfactuals to my bearish long-term outlook. I found some, but not nearly enough.
Early this year, I wrote a post “We are in depression”, which called the ongoing downturn a depression with a small ‘d.’ I was optimistic that policymakers could engineer a fake recovery predicated on stimulus and asset price reflation – and this was bullish for financial shares if not the broader stock market. But, we are witnessing temporary salves for a deeper structural problem.
So my goal was to find data which disproved my original thesis. But, I came away more convinced that we are in a tenuous cyclical upturn. This post will discuss why we are in a depression, not a recession and what this means about likely future economic and investing paths. I pull together a number of threads from previous posts, so it is pretty long. I have shortened it in order to pull all of the ideas into one post. So, please read the linked posts for background as I left out a lot of the detail in order to create this narrative.
Let’s start here then with the crux of the issue: debt.
Deep recession rooted in structural issues
Back in my first post at Credit Writedowns in March 2008, I said that the U.S. was already in a recession, the only question being how deep and how long. The issue was and still is overconsumption i.e. levels of consumption supported only by increase in debt levels and not by future earnings. This is the core of our problem – debt.
I see the debt problem as an outgrowth of pro-growth, anti-recession macroeconomic policy which developed as a reaction to the 1970s lost decade trauma in the U.S. and the U.K.. The 70s was a low growth, high inflation ride that generated poor market returns. The U.K. became the sick man of Europe and labor strife brought the economy to its knees. For the U.S., we saw the resignation of an American President and the humiliation of the Iran Hostage Crisis.
In essence, after the inflationary outcome that many saw as an outgrowth of the Samuelson-Keynesianism of the 1960s and 1970s, the Reagan-Thatcher era of the 1990s ushered in a more ‘free-market’ orientation in macroeconomic policy. The key issue was government intervention. Policy makers following Samuelson (more so than Keynes himself) have stressed the positive effect of government intervention, pointing to the Great Depression as animus, and the New Deal, and World War II as proof. Other economists (notably Milton Friedman, and later Robert Lucas) have stressed the primacy of markets, pointing to the end of Bretton Woods, the Nixon Shock and stagflation as counterfactuals. They point to the Great Moderation and secular bull market of 1982-2000 as proof. This is a divisive and extremely political issue, in which the two sides have been labeled Freshwater and Saltwater economists (see my post “Freshwater versus saltwater circa 1988”).
However, just as the policy of the 1950s to the 1970s was not really Keynesian ( see what Richard Posner says about Keynes’ General Theory and you will see why), the 1980s-2000 was not really an era of ‘free markets.’ I call it deregulation as crony capitalism. What this has meant in practice is that the well-connected, particularly in the financial services industry, have won out over the middle classes (a view I take up in “A populist interpretation of the latest boom-bust cycle”). In fact, hourly earnings peaked over 35 years ago in the United States when adjusting for inflation.
The 1970s was a difficult period in which the U.K. and the U.S. saw jobs vanish in key industrial sectors. To stop the rot and effectively mask the lack of income growth by average workers, a new engine of growth had to be found. Enter the financial sector. The financialization of the American and British economies began in the 1980s, greatly increasing the size and impact of the financial sector (see Kevin Phillips’ book “Bad Money”). The result was an enormous increase in debt, especially in the financial sector.
This debt problem was made manifest repeatedly during financial crises of the era. Not all of these crises were American – most were abroad and merely facilitated by an increase in credit, liquidity, and international capital movement. In March 2008, I wrote in my third post on the US economy in 2008:
From the very beginning, the excess liquidity created by the U.S. Federal Reserve created an excess supply of money, which repeatedly found its way through hot money flows to a mis-allocation of investment capital and an asset bubble somewhere in the global economy. In my opinion, the global economy continued to grow above trend through to the new millennium because these hot money flows created bubbles only in less central parts of the global economy (Mexico in 1994-95, Thailand and southeast Asia in 1997, Russia and Brazil in 1998, and Argentina, Uruguay, and Brazil in 2001-03). But, this growth was unsustainable as the global imbalances mounted.
Eventually, the debt burdens became too large and resulted in the housing meltdown and the concomitant collapse of the financial sector, a problem that our policymakers should have foreseen and the reason my blog is named Credit Writedowns. Make no mistake, the housing and writedown problems are only symptoms; the real problem is the debt – specifically an overly indebted private sector (note the phrase ‘private sector’ as I will return to this topic).
This is a depression, not a recession
When debt is the real issue underlying an economic downturn, the result is either Great Depression-like collapse or a period of stagnation and short business cycles as we have seen in Japan over the last two decades. This is what a modern-day depression looks like – a series of W’s where uneven economic growth is punctuated by fits of recession.
A garden-variety recession is merely a period of recalibration after businesses get ahead of themselves by overestimating consumption demand and are then forced to cut back by making staff redundant, paring back inventories and cutting capacity. Recessions can be overcome with the help of automatic stabilizers like unemployment insurance to cushion the blow.
Depression is another event entirely. Back in February, I highlighted a blurb from David Rosenberg which summed up the differences between recession and depression pretty well.
Recessions are typically characterized by inventory cycles – 80% of the decline in GDP is typically due to the de-stocking in the manufacturing sector. Traditional policy stimulus almost always works to absorb the excess by stimulating domestic demand. Depressions often are marked by balance sheet compression and deleveraging: debt elimination, asset liquidation and rising savings rates. When the credit expansion reaches bubble proportions, the distance to the mean is longer and deeper. Unfortunately, as our former investment strategist Bob Farrell’s Rule #3 points out, excesses in one direction lead to excesses in the opposite direction.
The day after I highlighted Ray Dalio’s version of this story which added some more color. Notice the part about printing money and devaluing the currency if the debt is in your own currency.
… economies go through a long-term debt cycle — a dynamic that is self-reinforcing, in which people finance their spending by borrowing and debts rise relative to incomes and, more accurately, debt-service payments rise relative to incomes. At cycle peaks, assets are bought on leverage at high-enough prices that the cash flows they produce aren’t adequate to service the debt. The incomes aren’t adequate to service the debt. Then begins the reversal process, and that becomes self-reinforcing, too. In the simplest sense, the country reaches the point when it needs a debt restructuring…
This has happened in Latin America regularly. Emerging countries default, and then restructure. It is an essential process to get them economically healthy.
We will go through a giant debt-restructuring, because we either have to bring debt-service payments down so they are low relative to incomes — the cash flows that are being produced to service them — or we are going to have to raise incomes by printing a lot of money.
It isn’t complicated. It is the same as all bankruptcies, but when it happens pervasively to a country, and the country has a lot of foreign debt denominated in its own currency, it is preferable to print money and devalue…
The Federal Reserve went out and bought or lent against a lot of the debt. That has had the effect of reducing the risk of that debt defaulting, so that is good in a sense. And because the risk of default has gone down, it has forced the interest rate on the debt to go down, and that is good, too.
However, the reason it hasn’t actually produced increased credit activity is because the debtors are still too indebted and not able to properly service the debt. Only when those debts are actually written down will we get to the point where we will have credit growth. There is a mortgage debt piece that will need to be restructured. There is a giant financial-sector piece — banks and investment banks and whatever is left of the financial sector — that will need to be restructured. There is a corporate piece that will need to be restructured, and then there is a commercial-real-estate piece that will need to be restructured.
The Fake Recovery
So where are we, then? We are in a fake recovery that could last as long as three or four years or could peter out very quickly in a double dip recession. You may have seen my April post on the fake recovery. Read it. I won’t cover that ground here. However, I will highlight how I came to believe in the fake recovery and how asset prices have played into this period (the S&L crisis played out nearly the same way). I see writedowns as core to the transmission mechanism of debt and credit problems to the real economy via reduced supply and demand for credit. Again, this is why my site is called Credit Writedowns.
In March, at the depths of the downturn I wrote:
The problem is the writedowns. You see, if you get $30 billion in capital from the government, but lose another $40 billion because of credit writedowns and loan losses, you aren’t going to be lending any money. To me, that says the downturn will only end when the massive writedowns end, not before.
The U.S. government has finally realized this and is now moving to stem the tide. Their efforts point in four directions:
Increase asset prices. If the assets on the balance sheets of banks are falling, then why not buy them at higher prices and stop the bloodletting? This is the purpose of the TALF, Obama’s mortgage relief program and the original purpose of the TARP.
Increase asset prices. If assets on the balance sheet are falling, why not eliminate the accounting rules that are making them fall? Get rid of marking-to-market. This is the purpose of the newly proposed FASB accounting rule change.
Increase asset prices. If asset prices on the balance sheet are falling, why not reduce interest rates so that the debt payments which are crushing debtors ability to finance those assets are reduced? This is why short-term interest rates are near zero.
Increase asset prices. If asset prices on the balance sheet are falling, why not create Public-Private partnerships to buy up those assets at prices which reflect their longer-term value? This is what Geithner’s Capital Assistance Program is designed to do.
So I lied, there is only one direction the government is headed: increase asset prices (or, at least keep them from falling). Read White House Economic Advisor Larry Summers’ recent prepared remarks to see what I mean. (Summers on How to Deal With a ‘Rarer Kind of Recession’ – WSJ)
I was more on target in my thinking here than I could have known. The mark-to-market model died and mark-to-make believe began. It was then that I knew a recovery was likely to take hold. And it was going to be bullish for bank stocks and the broader market. What you should realize is that, despite the remaining problems in credit cards, commercial real estate or high yield loans, limiting credit growth, the changes instituted by government definitely have meant 1. that banks will earn a shed load of money and 2. that house price declines have stalled, underpinning the asset base of lenders. This necessarily means an end to massive writedowns, a firming of banks’ capital base, and a reduction in private sector deleveraging. And the recent brouhaha over Citi’s favorable tax deal in exiting TARP should tell you the government will stop at nothing to keep accounting favorable for the big banks.
As for the recent asset-based economic reflation, be under no illusion that these measures ‘solve’ the problem. The toxic assets are still toxic and banks are still under-capitalized. But increased asset values and the end of huge writedowns has underpinned the banks and led to a rise in the broader market in a feedback loop that has been far greater than I could have imagined at this stage in the economic cycle.
The double dip or the economic boom?
So what’s next? A lot of the economic cycle is self-reinforcing (the change in inventories is one example). So it is not completely out of the question that we see a multi-year economic boom. Higher asset prices, lower inventories, fewer writedowns all lead to higher lending capacity, higher cyclical output, more employment opportunities and greater business and consumer confidence. If employment turns up appreciably before these cyclical agents lose steam, you have the makings of a multi-year recovery. This is how every economic cycle develops. This one is no different in this regard.
Now, I have turned slightly more dour of late and see a double dip as more likely in the medium-term. Longer-term, things depend on government because we are in a balance sheet recession. Ray Dalio and David Rosenberg make this case well in the previous quotes I supplied, but it was a post about Richard Koo from Prieur du Plessis which originally got me to write this post. His post, “Koo: Government fulfilling necessary function” reads as follows:
According to Koo, American consumers are suffering from a balance sheet problem and will not increase consumption until their personal finances are back in order. The banks are not lending mainly because nobody wants to borrow and, furthermore, the banks want to build their own balance sheets (raise cash) and get rid of toxic garbage…
Again, when asked what would happen if the government cuts back on its fiscal stimulus, Koo replies: “Until the private sector is finished repairing its balance sheets, if the government tries to cut its spending, we’re going to fall into the same trap Franklin Roosevelt fell into in 1937 (a crushing bear market) and Prime Minister Hashimoto fell into in 1997, exactly 70 years later.
“The economy will collapse again and the second collapse is usually far worse than the first. And the reason is that, after the first collapse, people tend to blame themselves. They say, ‘I shouldn’t have played the bubble. I shouldn’t have borrowed money to invest – to speculate on these things.’
I wrote last November that if government stops the support, recession is going to happen.
The U.S. economy cannot possibly work itself out of the greatest financial crisis in some 70-odd years in a mere 4 years and then expect to raise taxes on the middle class without a major recessionary relapse.
So, when you hear policy makers talking about reducing the deficit as soon as possible, what you should think is 1938 and continued depression.
Right now, if you listen to what President Obama is likely to do, you know that the government prop for the economy is going to be taken away. Get ready because the second dip will occur. It will be nasty: unemployment will be higher and stocks will go lower than in 2009. I The question now is one of timing: when will the government stop propping up the economy? The more robust the recovery, the quicker the prop ends and the sooner we get a second leg down.
So to recap:
A depression was borne out of high levels of private sector debt, the unsustainability of which became apparent after a financial crisis.
The effects of this depression have been lessened by economic stimulus and government support.
Government intervention led to a reduction in asset price declines, which led to stock market increases, which led to asset price stabilization and more stock market increases and eventually to asset price increases. This has led to a false sense that green shoots are leading to a sustainable recovery.
In reality, the problems of high debt levels in the private sector and an undercapitalized financial system are still lurking, waiting for the government to withdraw its economic support to become realized
Because large scale government deficit spending is politically unpalatable and unsustainable over the long-term, expect a second economic dip within three to four years at the latest.
Why is government spending key?
The government plays a crucial role here because of the huge private sector indebtedness. In the U.S. and the U.K., the public sector is not nearly as indebted. So while, the private sector rebuilds its savings and reduces debt, the public sector can pick up the slack. Marshall Auerback says it best in a recent post:
We’ve said it before and we’ll say it again. As a matter of national accounting, the domestic private sector cannot increase savings unless and until foreign or government sectors increase deficits. Call this the tyranny of double entry bookkeeping: the government’s deficit equals by identity the non-government’s surplus.
So, if the US private sector is to rebuild its balance sheet by spending less than its income, the government will have to spend more than its tax revenue. The only other possibility is that the rest of the world stops saving on a massive scale — letting the US run a current account surplus. But that is highly implausible and socially undesirable, since it means we export our economic output, rather than consume it domestically. And if the government deficit does not grow fast enough to meet the saving needs of the private domestic sector, national income will decline, which, given the size of the private sector’s debt problem, will generate a huge debt deflation.
This is the foundation of modern monetary theory. Would that the IMF and the G20 understood these basic facts.
If the private sector is a net saver, the public sector must run a deficit. The only other way to prevent the government from running a deficit when the private sector is net saving is to run huge current account surpluses by exporting your way out of recession – what Germany and Japan tried in the 1990s and in this decade.
However, I must admit to having a preternatural disaffection for large deficits and big government which is what Koo and Minsky advise respectively. It is this knee-jerk aversion to what is viewed as fiscal profligacy which makes it likely that the government prop will be taken away inducing another downturn.
So, what does this mean for the American and global economy?
The private sector (particularly households) is overly indebted. The level of debt households now carry cannot be supported by income at the present levels of consumption. The natural tendency, therefore, is toward more saving and less spending in the private sector (although asset price appreciation can attenuate this through the Wealth Effect). That necessarily means the public sector must run a deficit or the import-export sector must run a surplus.
Most countries are in a state of economic weakness. That means consumption demand is constrained globally. There is no chance that the U.S. can export its way out of recession without a collapse in the value of the U.S. dollar. That leaves the government as the sole way to pick up the slack.
Since state and local governments are constrained by falling tax revenue (see WSJ article) and the inability to print money, only the Federal Government can run large deficits.
Deficit spending on this scale is politically unacceptable and will come to an end as soon as the economy shows any signs of life (say 2 to 3% growth for one year). Therefore, at the first sign of economic strength, the Federal Government will raise taxes and/or cut spending. The result will be a deep recession with higher unemployment and lower stock prices.
Meanwhile, all countries which issue the vast majority of debt in their own currency (U.S, Eurozone, U.K., Switzerland, Japan) will inflate. They will print as much money as they can reasonably get away with. While the economy is in an upswing, this will create a false boom, predicated on asset price increases. This will be a huge bonus for hard assets like gold, platinum or silver. However, when the prop of government spending is taken away, the global economy will relapse into recession.
I believe this dynamic will induce a Scylla and Charybdis of inflationary and deflationary forces, forcing central bankers to add and withdraw liquidity in a manic way. The likely volatility in government spending and taxation gives you the makings of a depression shaped like a series of W’s consisting of short and uneven business cycles. The secular force is the D-process and the deleveraging, so I expect deflation to be the resulting secular trend more than inflation.
Needless to say, this kind of volatility will induce a wave of populist sentiment, leading to an unpredictable and violent geopolitical climate and the likelihood of more muscular forms of government.
From an investing standpoint, consider this a secular bear market for stocks then. Play the rallies, but be cognizant that the secular trend for the time being is down. The Japanese example which we are now tracking is a best case scenario.
That’s my thesis. What’s your view?
Subscribe to:
Posts (Atom)